Policy Gridlock, Lipid Tightness, and the Biofuel Ceiling

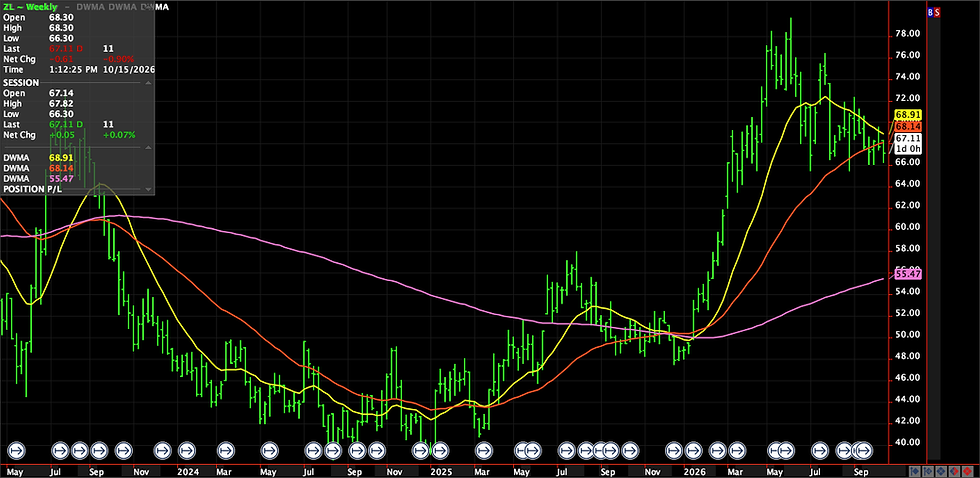
As Washington’s shutdown drags on, the conversation across U.S. agriculture has turned from frustration to self-examination. Soybean exports remain the focal point of the political blame game, especially as new USTR port taxes on Chinese vessels threaten to aggravate the rift with America’s largest soy buyer. The timing could hardly be worse—harvest progress is nearing 40%, and with bins filling rapidly, the next two weeks will likely expose storage and transport bottlenecks. While the administration defers a domestic farm-aid program until the government reopens, it quietly authorized a $20 billion foreign-exchange support for Argentina, raising questions about priorities. USDA is not idle, however. Southeast Asian buyers from Indonesia, Vietnam, and Thailand toured U.S. soybean farms this week under the Northern Soy Marketing initiative, part of a push to cultivate non-Chinese markets. These visits emphasize amino-acid profiles and reliability of supply—differentiators against South American beans with higher protein but more volatile logistics. Farmers’ message is simple: “We just need to sell some soybeans.” Yet margins remain deeply negative, with cash-flow models showing losses near $170 per acre for soybeans and $190 per acre for corn, leaving even experienced growers on edge. In the U.S. biofuels complex, D4 RINs slipped to $1.04 while the biodiesel screen-crush margin remains near –50 ¢/gal, keeping producers reluctant to hedge amid uncertain 45Z guidance. Road-diesel consumption continues to track below last year, and policy volatility has left buyers sidelined. While ethanol demand shows slight resilience thanks to slower EV adoption and stronger gasoline draw, biodiesel and RD output remain capped by feedstock costs and muted confidence.
Want to read more?
Subscribe to globalbiodiesel.com to keep reading this exclusive post.